

"Why Not Just Go to My Own Bank?"
It's a fair question, and one that comes up again and again among UAE residents and overseas buyers deciding whether to use a Dubai mortgage broker. If you already have an account with a local bank, going to it directly can seem like the simplest option. The problem is that you will only see that one bank's offer, with no idea how it compares with what else is on the market.
A Dubai Mortgage Broker Sees the Whole Market, Not Just One Bank
Every lender structures its offer slightly differently: the interest rate, processing fees, the option to make early repayments without a penalty, discounts tied to salary transfer, and more.
Without comparing several banks, you have no way of knowing whether the offer you received is genuinely competitive, or whether another bank would have offered significantly better terms.
A broker's core value is doing that comparison for you and pointing you to the bank that suits your situation, rather than settling for the bank where you already hold an account.
Matching the Mortgage to Your Plans
A standard mortgage is not necessarily the right mortgage for you.
Practical example: A buyer takes out a 20-year mortgage but plans to pay it off within five or six years. Under UAE Central Bank rules, most banks may charge an early settlement fee of up to 1% of the outstanding balance or AED 10,000, whichever is lower.
So if the outstanding balance is AED 1,500,000, the fee is capped at AED 10,000 rather than a full 1%. A broker who knows the buyer's plans in advance can go further and direct them to a bank that allows early repayments with no fee at all.
Rate comparison example (illustrative figures): A buyer goes to their own bank and is offered a 4.5% variable rate on an AED 2,000,000 mortgage. Before signing, they approach a mortgage broker, who submits the same case to four other banks:
| Lender | Rate offered | Annual difference vs the buyer's bank |
|---|---|---|
| Buyer's bank | 4.50% | No difference |
| Bank B | 4.70% | AED 4,000 more per year |
| Bank C | 4.60% | AED 2,000 more per year |
| Bank D | 4.15% | AED 7,000 saved per year |
| Bank E | 4.55% | AED 1,000 more per year |
One bank offers 4.15% on the same loan terms. A 0.35% difference could save around AED 7,000 a year and around AED 175,000 over a 25-year term.
The buyer's usual bank would not have told them that a competitor was offering better terms. The only way to know is to compare.
Brokers Know Which Banks Are Likely to Approve You
One of the most underrated advantages of working with a broker is knowing in advance which bank is likely to approve a given profile.
Applying to a bank that doesn't fit the applicant's documents or financial situation can lead to an unnecessary rejection. That's not a disaster, but it may have some effect on your credit score with the Al Etihad Credit Bureau (AECB).
A broker who knows each bank's credit policy can steer you from the start to the lender most likely to approve you.
Does the Service Cost Anything?
In many cases, especially for salaried residents with clear, documented income, the mortgage broker charges the client no fee at all, because they are paid by the lending bank.
A client fee is usually only charged on more complex cases that need extra work to get approved. Either way, it's worth confirming the fee structure for your case upfront.
The Bottom Line
Going straight to your own bank may look simpler, but it means accepting a single lender's offer with no real way to compare.
A Dubai mortgage broker's job is to check the market for you, match you with a bank more likely to approve your application and structure the loan around your plans, often at no direct cost to you.
In Dubai, mortgage brokerage is a RERA-licensed activity. So before you start working with a professional, check that they appear in the RERA licensed brokers registry on the Dubai Land Department's official website.
Area Spotlight: Jumeirah Village Circle
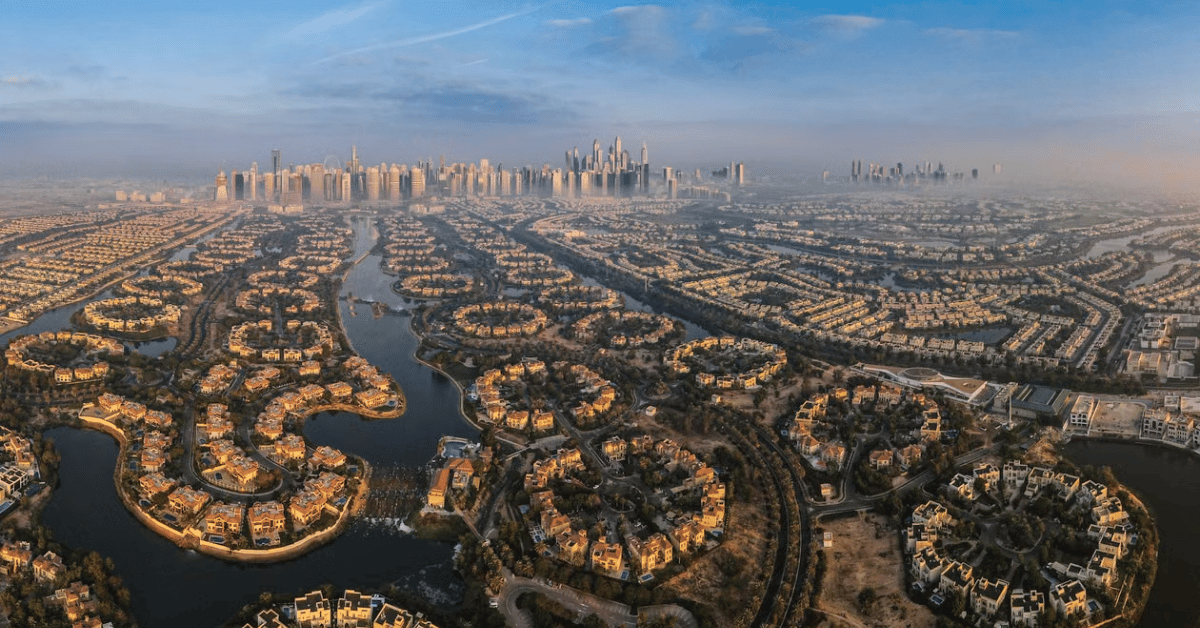
Jumeirah Village Circle (JVC) is a great example of the value of professional advice. It's a high-transaction-volume area where financing terms vary noticeably between banks, so comparing the market has real financial impact.
Location: 6 | Developer: 7 | Concept: 7 | Pricing: 9 | Rental: 8 | Appreciation potential: 6 | Liquidity: 8
Verdict: The area's big strengths are accessible prices and high transaction volume. That's exactly the kind of market where a broker's ability to compare banks pays for itself.
FAQs
Do I have to pay a mortgage broker in Dubai? Often not. In straightforward cases for salaried residents, many brokers are paid by the bank rather than the client. A fee is usually only charged on more complex cases.
Will applying to several banks or using a broker hurt my credit score? An application submitted to an unsuitable bank that ends in rejection may slightly affect your credit score. A broker reduces that risk by matching your application to a bank more likely to approve it.
Can a broker help me pay off my mortgage early without penalties? In many cases, yes. Some banks allow early repayments or full settlement with no fee. If the broker knows your plans in advance, they can choose a suitable lender from the start.
Is a broker worth it if I already have a UAE bank account? Usually, yes. Your bank can only show you its own offer, while a broker can check whether it's genuinely competitive against the market.
Further Reading
This guide is part of Dubai Index's comprehensive mortgage content hub. For the full picture, read our complete guide to mortgages in Dubai.
Other guides you may find useful:
- The Dubai mortgage process, step by step
- Non-resident mortgages in Dubai
- UAE company mortgages
- Dubai Index mortgage and financing service
We recommend contacting Dubai Index directly to check current fee arrangements. In most cases they are agreed with the partner bank on a case-by-case basis and are not published on a public offers page.
Ready to Find the Right Mortgage Solution?
Dubai Index connects buyers with trusted mortgage brokers and financing routes tailored to their profile. Contact Dubai Index to find the right bank for your case.